


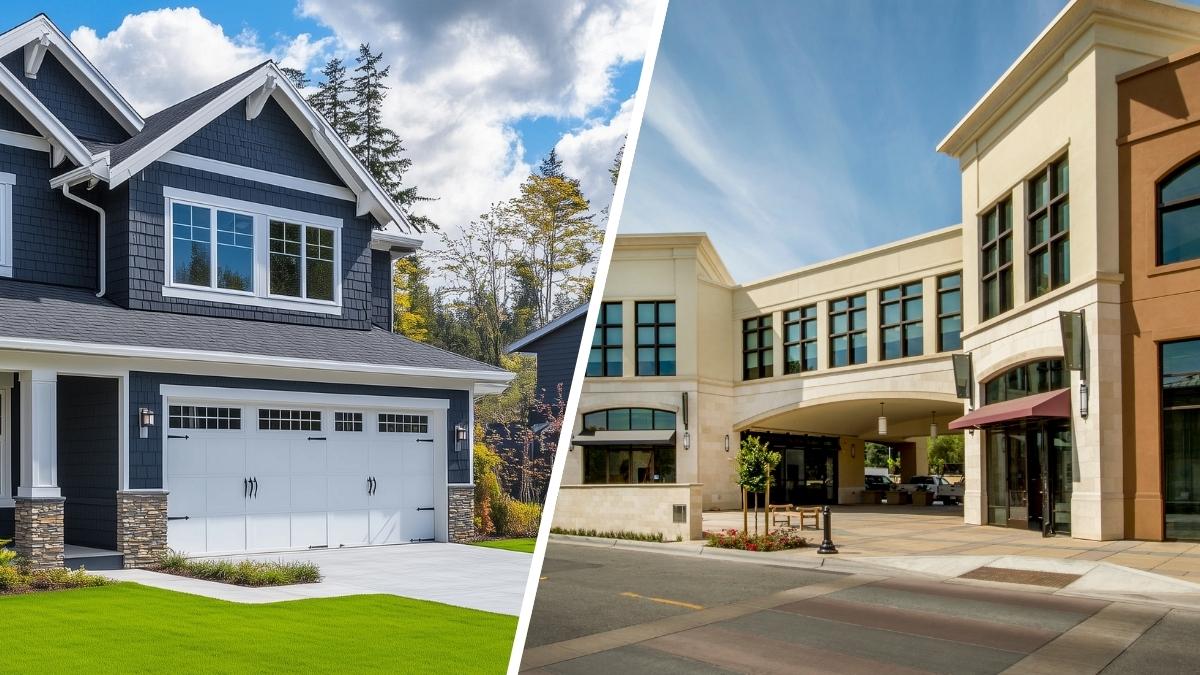
- Residential property is generally easier to finance, manage and sell, making it a popular choice for first-time investors seeking long-term capital growth.
- Commercial property can deliver higher rental yields, longer lease terms and lower ongoing expenses, but usually requires more capital and comes with greater vacancy and financing risks.
- The better investment depends on an investor's goals, with residential property often favoured for growth and commercial property for income and cash flow.
For many Australians, property investing starts and ends with residential real estate. A house, apartment or townhouse feels familiar, and it's the asset class most people understand. But for those willing to broaden their horizons, commercial property offers an alternative avenue for investment.
Commercial property, which includes everything from retail premises and office space to industrial warehouses, has long attracted investors chasing stronger rental returns.
It's also become a popular consideration for some self-managed super funds (SMSFs), particularly following recent changes to SMSF borrowing rules.
The catch is that higher potential income often comes with higher complexity. Commercial properties can be harder to finance, more expensive to buy and riskier to leave vacant.
Residential properties, on the other hand, are generally easier to understand and sell, but may deliver lower yields.
If you're considering either route, here's what you need to know about the key differences.
At a glance: Residential vs commercial property
While both residential and commercial property can generate rental income and long-term capital growth, they differ in some important ways.
|
Factor |
Residential property |
Commercial property |
|
Typical assets |
Houses, apartments, townhouses |
Offices, retail shops, warehouses, industrial properties |
|
Rental yields |
Generally lower |
Generally higher |
|
Capital growth |
Historically driven by housing demand and population growth |
Often linked to business activity and economic conditions |
|
Lease length |
Typically 6 to 12 months |
Often 3 to 10+ years |
|
Vacancy risk |
Demand tends to be broader |
Vacancies can last longer, particularly during economic downturns |
|
Upfront costs |
Lower entry point for most investors |
Higher purchase prices and larger deposits are common |
|
Finance requirements |
Generally easier to obtain lending |
Lenders may require larger deposits and stricter assessments |
|
Property expenses |
Landlords often cover most outgoings and maintenance costs |
Tenants may pay some outgoings under commercial lease agreements |
|
Investor profile |
Often suits first-time and long-term investors |
Often attracts experienced or income-focused investors |
How do financing requirements differ?
Financing is often where residential and commercial property diverge.
Residential loans are generally easier to obtain, with lenders commonly offering LVRs of 80% or more, depending on the borrower. Commercial property loans typically require larger deposits, with LVRs often capped at around 60% to 70%.
Lenders also assess commercial loans more closely. Alongside your financial position, they may consider factors such as the property's location, tenant quality, lease length and vacancy risk.
Interest rates can also be higher, reflecting the greater risk associated with commercial property.
In short, residential property is usually easier and cheaper to finance, while commercial property often requires more capital, stricter lending assessments, and a stronger buffer against potential vacancies.
Pros and cons of residential property
Pros of residential property
Lower barrier to entry
Compared with commercial property, residential investments typically require less capital upfront. Lenders are generally more comfortable financing houses and apartments, which can make it easier for investors to secure a loan and enter the market.
Broad tenant demand
People will always need somewhere to live. While rental demand varies between locations, residential properties generally appeal to a larger pool of tenants than commercial premises, helping reduce the risk of prolonged vacancies.
Strong long-term capital growth potential
Historically, residential property has delivered solid capital growth in many Australian markets, particularly in areas benefiting from population growth, infrastructure investment and limited housing supply.
Easier to buy and sell
The residential market is larger and more liquid than the commercial market. There are typically more buyers, which can make it easier to sell a property when the time comes.
Simpler for first-time investors
Residential property is generally easier to understand and manage. Lease arrangements tend to be less complex, and there is usually a wider range of property managers and support services available.
Cons of residential property
Lower rental yields
Residential properties often generate lower rental returns than commercial assets. This can make it harder for the rental income alone to cover mortgage repayments and other ownership costs.
Shorter lease terms
Most residential leases run for six or 12 months, meaning tenants may move more frequently. Higher turnover can lead to vacancy periods and additional costs associated with finding new tenants.
Landlords typically cover most expenses
Property owners are usually responsible for maintenance, repairs, council rates, insurance and other outgoings. These costs can have a significant impact on investment returns over time.
Greater exposure to tenant-related issues
Rent arrears, property damage and tenant disputes can occur in any rental property. While these risks can be managed, they remain an ongoing consideration for residential investors.
Returns can depend heavily on capital growth
Many residential investors rely on a property's value increasing over time rather than generating strong rental income. If housing price growth slows or stalls, overall returns may be lower than expected.
Pros and cons of commercial property
Pros of commercial property
Higher rental yields
Commercial properties often generate stronger rental returns than residential assets, particularly in sectors such as industrial, warehouse and retail property. While yields vary by location and tenant quality, the higher income potential can make commercial property attractive to investors focused on cash flow rather than relying primarily on capital growth.
Longer lease agreements
Commercial leases commonly run for several years and may include options to extend, providing greater income certainty for landlords. Longer lease terms can reduce tenant turnover and minimise the costs and disruptions associated with regularly advertising and re-leasing a property.
Tenants may cover property outgoings
Many commercial leases require tenants to contribute to expenses such as council rates, building insurance, maintenance and other operating costs. This arrangement can reduce the landlord's ongoing expenses and improve the net return generated by the investment.
Professional tenant relationships
Commercial tenants are often businesses with a vested interest in remaining in the same location for operational and customer reasons. This can create longer-lasting landlord-tenant relationships and may reduce some of the day-to-day management issues commonly associated with residential rentals.
Cons of commercial property
Higher entry costs
Commercial properties typically have higher purchase prices, larger deposit requirements and more expensive transaction costs than residential investments. This can make commercial property less accessible for first-time investors and may require significantly more capital to get started.
Greater vacancy risk
While commercial leases are usually longer, finding a replacement tenant can take much longer when a property becomes vacant. Demand is often more specialised, meaning vacancies can last for months and leave owners without rental income during that period.
More sensitive to economic conditions
The performance of commercial property is closely tied to business activity and broader economic trends. Economic downturns, changes in consumer spending or shifts in workplace practices can affect tenant demand, rental growth and property values.
Financing can be more difficult
Lenders generally view commercial property as a higher-risk investment and may apply stricter lending criteria. Investors may need to provide larger deposits, demonstrate stronger financial positions or pay higher interest rates compared with residential borrowers.
Property values can be harder to predict
Commercial property values are heavily influenced by factors such as tenant quality, lease terms, vacancy rates and local business conditions. This means price growth can be less consistent than residential property, and investors may find it more difficult to sell quickly when market conditions weaken.
Can you buy residential or commercial property through an SMSF?
Yes, but the rules have changed. An SMSF can still buy both residential and commercial property, however, since 10 August 2026, it can generally no longer use a new limited recourse borrowing arrangement (LRBA) to purchase residential property. Existing residential SMSF loans are protected and can still be refinanced.
That makes commercial property the easier option for SMSFs that want to borrow. Funds can still use LRBAs to acquire eligible business real property, which is why some business owners choose to buy their premises through super and lease it back to their business on market terms.
Whichever route you take, the rules are strict. You generally can't live in, or rent, a residential property owned by your SMSF, and all property transactions must be conducted at arm's length.
Which is better for investors?
There's no clear winner when it comes to residential versus commercial property. The better investment depends on what you're trying to achieve.
Residential property is often favoured by investors chasing long-term capital growth, while commercial property tends to appeal to those seeking stronger rental income and cash flow.
Your risk tolerance and budget also matter. Residential properties are generally easier to finance, attract a broader pool of tenants and require less upfront capital. Commercial properties can deliver higher yields, but vacancies can last longer and lending requirements are often stricter.
For many investors, the choice comes down to growth versus income. Residential property may suit those looking for a lower-maintenance entry into investing, while commercial property can appeal to investors willing to take on more complexity in exchange for potentially higher returns.
Some investors ultimately hold both, using each asset class for a different role within their portfolio.
Image created via Canva
Speak to an SMSF lending specialist
Whether you're looking to refinance or purchase investment property with your SMSF our partners can help you find the right SMSF loan.

